Santa Clarita Personal Injury Resources
Practical, plain-English tools for understanding the injury claims process, from how it works to what things mean.
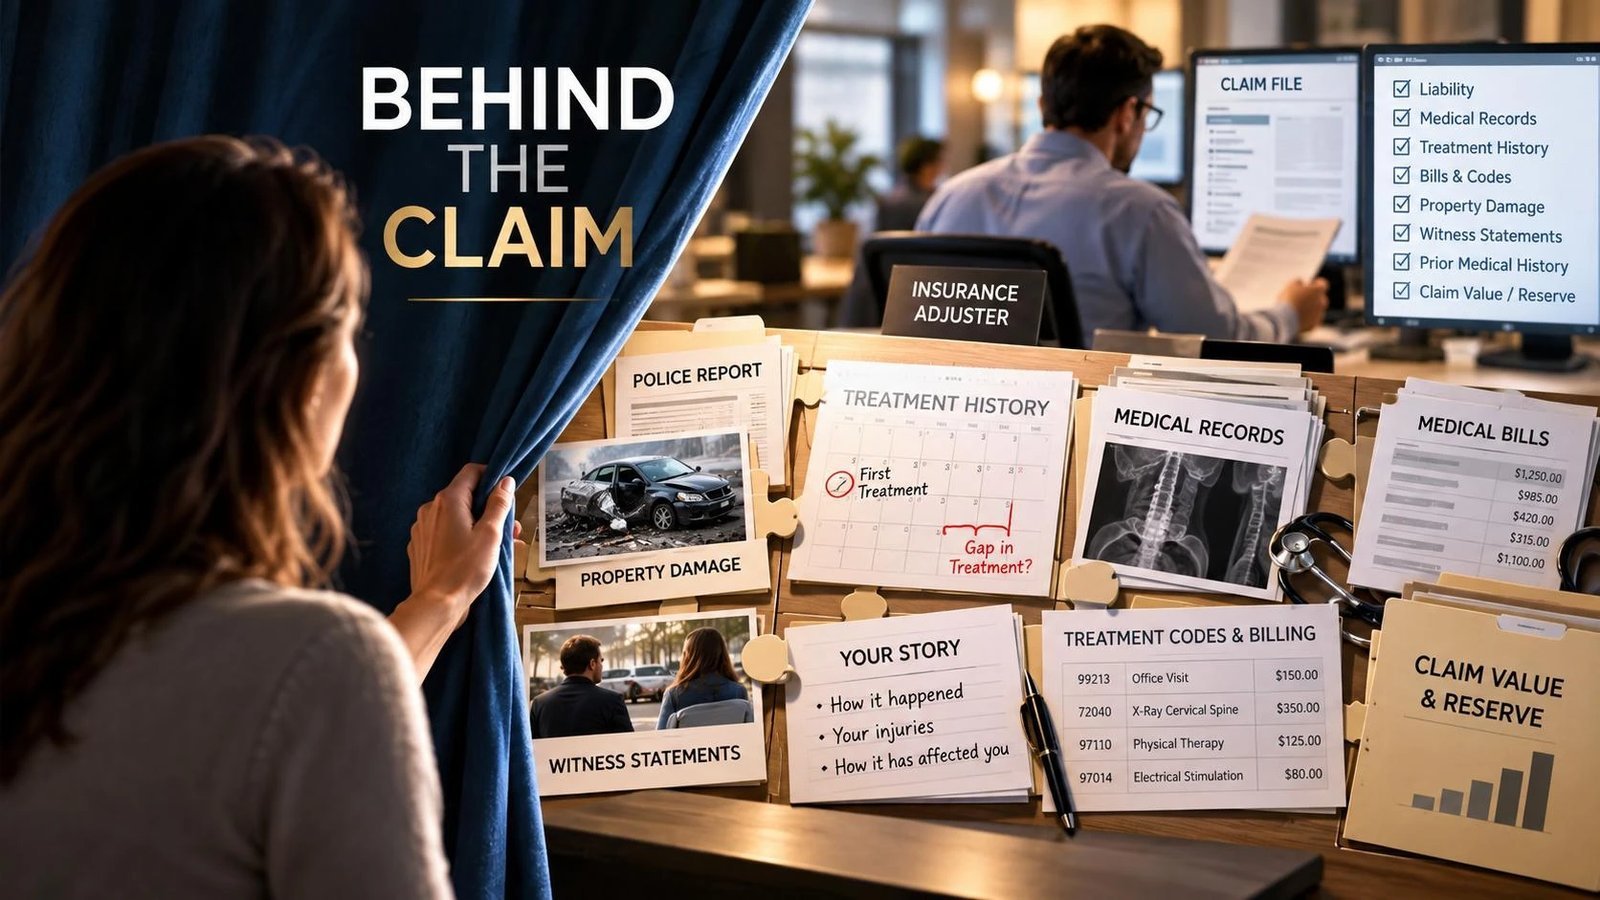
A personal injury claim is more than a stack of medical bills and a letter asking an insurance company to pay. Behind the scenes, the insurer weighs how the accident happened, who may be responsible, what the property damage shows, when treatment began, what the records say, and how well the pieces of evidence fit together. These resources explain those nuts and bolts, whether you have an attorney or are handling a claim on your own.
Key Takeaways
- Insurance companies evaluate the entire claim, not just the medical bills. Liability, property damage, medical records, treatment, witnesses, and credibility can all count.
- The timing of medical care can matter. Adjusters and defense attorneys commonly look at when treatment began and whether there are gaps.
- Evidence should tell a consistent story. Photographs, medical records, witness testimony, imaging, and employment records help establish what happened and how it affected you.
- Treatment may be scrutinized. Insurers may question the type, duration, frequency, and cost of care rather than accepting every bill.
- The evaluation changes as information develops. New records, bills, imaging, or witness information can shift how a claim is viewed.
- Understanding the process helps you make better decisions and avoid mistakes that could come back to haunt you later.
Resources for Understanding Your Personal Injury Claim
These work together rather than as isolated articles. Start with the subject that concerns you most, then explore the others.
How Personal Injury Cases are Evaluated
What does an insurance adjuster actually look at when evaluating a personal injury claim?
Read guide →Medical Liens and Bills
How medical billing, health insurance, and liens interact with a claim, explained in plain English.
Read guide →What is the Value of Your Injury Claim?
The real factors that affect a claim's value, explained honestly, without false promises or formulas.
Read guide →Personal Injury Glossary
English definitions for the legal and insurance terms you're likely to encounter.
Browse the Glossary →Evidence and Documentation
What kind of evidence actually matters, and practical ways to preserve it before it's gone.
Read guide →Personal Injury FAQs
Quick, direct answers to the questions people ask most.
Browse the FAQs →
What Happens Behind the Scenes?
The insurance company is evaluating the claim throughout the process. An adjuster is not simply waiting for the final medical bill and then deciding what to pay.
The calendar
An adjuster or defense attorney may look at when treatment began after the accident. A significant delay, or a gap in care, can become an issue.
The medical care
The duration, frequency, and cost of treatment may be questioned, along with whether the records support the care provided.
The systems
Insurers may use computerized systems and medical reviews to analyze records and billing. Reviewing professionals may disagree with the treating doctors.
The reserve
Adjusters commonly set an internal reserve, an amount set aside based on the claim's assessed value or exposure. It may be adjusted as facts develop.
Keeping the insurer reasonably informed as significant information develops can matter in a larger claim, because the reserve and the evaluation move with the file. None of this means the insurer's evaluation is correct. It means a claim is analyzed from several angles, often long before anyone makes a final settlement decision.
The Pieces of the Puzzle
A claim is made of many pieces: the accident itself, liability, property damage, photographs, witnesses, treatment, records, imaging, prior medical history, lost income, insurance coverage, and the injured person's credibility.
Pieces that reinforce each other
Photographs of substantial vehicle damage, prompt treatment, consistent records, objective imaging, and testimony from people who knew the injured person before and after the accident can all support the same picture.
Pieces that raise questions
Treatment delays, gaps in care, inconsistent statements, significant changes in medical history, or evidence that seems at odds with the claimed injuries may be investigated.
Not every claim needs every type of evidence. The claim is generally evaluated as a whole, and the strength of one piece depends partly on how it fits with the rest.
Understanding the Bigger Picture
The three sections of this site are designed to work together, and they cover not just what happened but what happens next and why.
Accident Guides
Issues specific to car, motorcycle, pedestrian, truck, slip and fall, and dog bite accidents.
Explore →Navigating the Claim
The development of a claim, from immediate steps through medical care, insurance communications, liability, and settlement.
Explore →Resources (this section)
The nuts and bolts of evaluating and presenting a claim: evidence, medical bills, valuation, terminology, and frequently asked questions.
Do You Need Legal Advice?
Not every claim requires an attorney. Straightforward claims with minor injuries, clear liability, and limited damages may be handled directly with the insurance company.
Legal guidance can become useful when:
- Injuries are serious or permanent
- Liability or comparative fault is disputed
- Multiple parties are involved
- Medical treatment is substantial
- Insurance coverage is complicated
- Future damages are possible
- Liens are significant
- The insurer has made a substantial settlement offer
The more complicated the pieces become, the more important it is to understand how they fit together before making decisions. The lawyer page and the filing deadlines page are good next stops.
Important: The information on this website is provided for educational purposes and is not a substitute for legal advice about a particular accident or claim. California personal injury law can depend heavily on the specific facts and circumstances involved.